 By
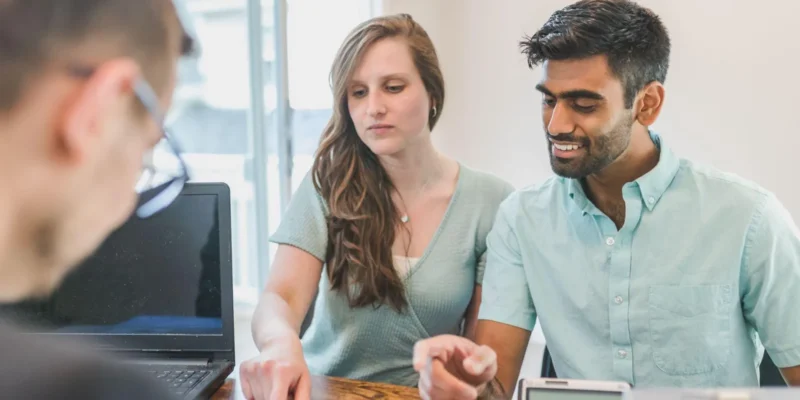
Planning a wedding takes an incredible amount of time, energy, and money. You spend months picking out the perfect venue, tasting cakes, and finalizing guest lists for a single day of celebration. But while you prepare for the wedding, you also need to prepare for the marriage itself. Money remains one of the leading causes of divorce, yet many couples avoid discussing their finances until a crisis hits. Sitting down with a financial advisor before you walk down the aisle changes that dynamic entirely. Bringing a neutral professional into the conversation early on takes the stress out of money talks. It sets a healthy baseline for how you’ll manage your combined wealth, ensuring you both step into this new chapter with your eyes wide open.
Table of Contents
Uncovering Hidden Habits and Attitudes
We all grow up with different attitudes about money based on our unique backgrounds. You might be a natural saver who tracks every penny, while your partner prefers to spend freely and enjoy the moment. Neither approach is inherently wrong, but blending them under one roof often causes tension. A professional acts as an objective mediator. They ask the tough questions about your spending habits, credit histories, and personal money anxieties in a safe, judgment-free environment.
Instead of arguing over who spends too much on weekend outings, you get to explore the deeper reasons behind those habits. Perhaps one of you grew up in a household where money was tight, leading to a lingering fear of unexpected expenses. This guided conversation helps you understand your partner’s financial mindset, building empathy rather than resentment. You’ll quickly learn how to communicate about your budget without placing blame.
Creating a Strategy for Existing Debt
It’s incredibly common to enter a marriage with some financial baggage, whether that involves student loans, a car note, or lingering credit card balances. When you get married, those individual debts suddenly impact your joint future. If you want to buy a house together, a mortgage lender looks at your combined debt-to-income ratio and both of your credit scores. Hiding debt or ignoring it won’t make it disappear.
Sitting down with an expert allows you to lay all your cards on the table. They’ll help you build a strategic payoff plan that makes sense for your new combined income. You’ll learn whether it’s better to quickly pay down high-interest accounts first or focus on consolidating smaller balances for better cash flow. Having a clear roadmap prevents debt from becoming a dark cloud over your first few years of marriage. It transforms an individual burden into a team challenge that you can conquer together.
Deciding How to Merge Your Accounts
One of the biggest logistical hurdles newlyweds face is figuring out how to actually manage their paychecks. Should you combine everything into a single joint checking account? Should you keep everything completely separate and split the bills down the middle? Maybe you want a hybrid approach, maintaining a joint account for household expenses while keeping individual accounts for personal fun money.
There isn’t a single right answer that works for everyone. An advisor helps you evaluate the pros and cons of each method based on your specific income levels and spending styles. They’ll guide you toward a banking structure that fosters transparency while still giving you both a sense of personal financial independence. Getting this administrative framework set up before the honeymoon saves you from awkward conversations at the grocery store checkout line later on.
Aligning Your Long-Term Goals
You probably already talked about your dreams for the future. You might want to buy a starter home in the suburbs, take a yearly vacation abroad, or start a family within the next five years. Dreaming is the easy part; funding those dreams requires serious math. A professional helps you attach realistic price tags to your shared life goals.
If you want to buy a house in three years, they’ll show you exactly how much you need to save each month for the down payment. If you want to retire by sixty, they’ll calculate the exact percentage of your paychecks that needs to go into your investment accounts right now. This transforms vague wishes into concrete, actionable steps. You walk away with a unified master plan, knowing exactly where your money needs to go each month to build the life you both want.
Protecting Your Growing Family
Marriage isn’t just a romantic partnership; it’s a legal and financial contract. When you tie the knot, you become responsible for each other’s well-being. This means you need to start thinking about things you probably ignored when you were single, like life insurance, disability coverage, and estate planning.
It isn’t the most fun topic to discuss, but it’s vital for protecting the life you’re building together. An expert points out the gaps in your current coverage and recommends the right policies to ensure your partner won’t face financial ruin if the unexpected happens. Getting these protections in place early brings incredible peace of mind.
Talking about money before the wedding doesn’t mean you lack trust or romance. It actually proves the exact opposite. It shows that you care enough about the relationship to build a rock-solid foundation before the honeymoon even begins. A professional provides the tools, the math, and the objective perspective you need to merge your lives successfully. When you take the time to align your financial habits and goals early on, you eliminate the money arguments that plague so many young couples. You get to start your marriage focused on enjoying your life together, confident that your financial future is completely secure.

Comments